retained
useful
Liquidity bridge
A Lombard loan: fund your project without selling your investments. Keep a safety margin
A Lombard loan provides access to cash against your invested assets. Its resilience depends on the headroom, the agreement and how it handles a fall in asset values.
Obtaining liquidity without selling its assets does not remove the risk.
It moves him.
40 minutes · Confidential · No obligation · Directly with Gary Martins
5.011 Google reviewsPrivate advice · Your priorities first
Fund your project while keeping room to manoeuvre
-
Compare your financing options
Compare selling investments, borrowing and using cash you already have.
-
Look at the total cost
Review the interest, fees, term and repayment conditions, not just the amount you could borrow.
-
Plan for a fall in value
Check the collateral terms and the risk of a forced sale before pledging your investments.
Planning a purchase or a loan? Check feasibility before signing. The loan remains subject to the lender's approval.
Direct response
Borrow against your investments: what are the conditions?
A Lombard loan is a financing secured by financial assets or a like security, according to the contract, establishment and jurisdiction. The assets are not sold immediately: they are used as collateral.
The lender applies a reduction, or haircut, to market value when calculating collateral value. Its rules take account of liquidity, volatility, concentration, currency and the type of assets.
As well as asking how much you can borrow, consider the margin left if your investments fall, interest rates rise or the exchange rate or project changes unfavourably.
The real question: what margin can you keep if the scenario becomes less favourable?
How it works
How does the loan work?
Start with the project, then examine the financing and the margin you would need if conditions become less favourable.
-
You need money for a project while your wealth remains invested. Compare selling, waiting, borrowing and reconsidering the project.
-
Selling can trigger tax, crystallise a loss or end an investment you wanted to keep. Borrowing lets you keep the assets, but adds debt and contractual obligations.
-
Part of the value of your investments secures the loan. The lender makes funds available when it considers the collateral sufficient.
-
If collateral value falls, your remaining margin shrinks. An initially comfortable position can become restrictive.
-
Set a borrowing amount you can withstand in a downturn before it happens, rather than waiting for a margin call.
How it works
How much headroom will you have after borrowing?
The bank assesses eligible assets, applies a haircut to their value, sets a borrowing limit and monitors the remaining headroom throughout the loan.
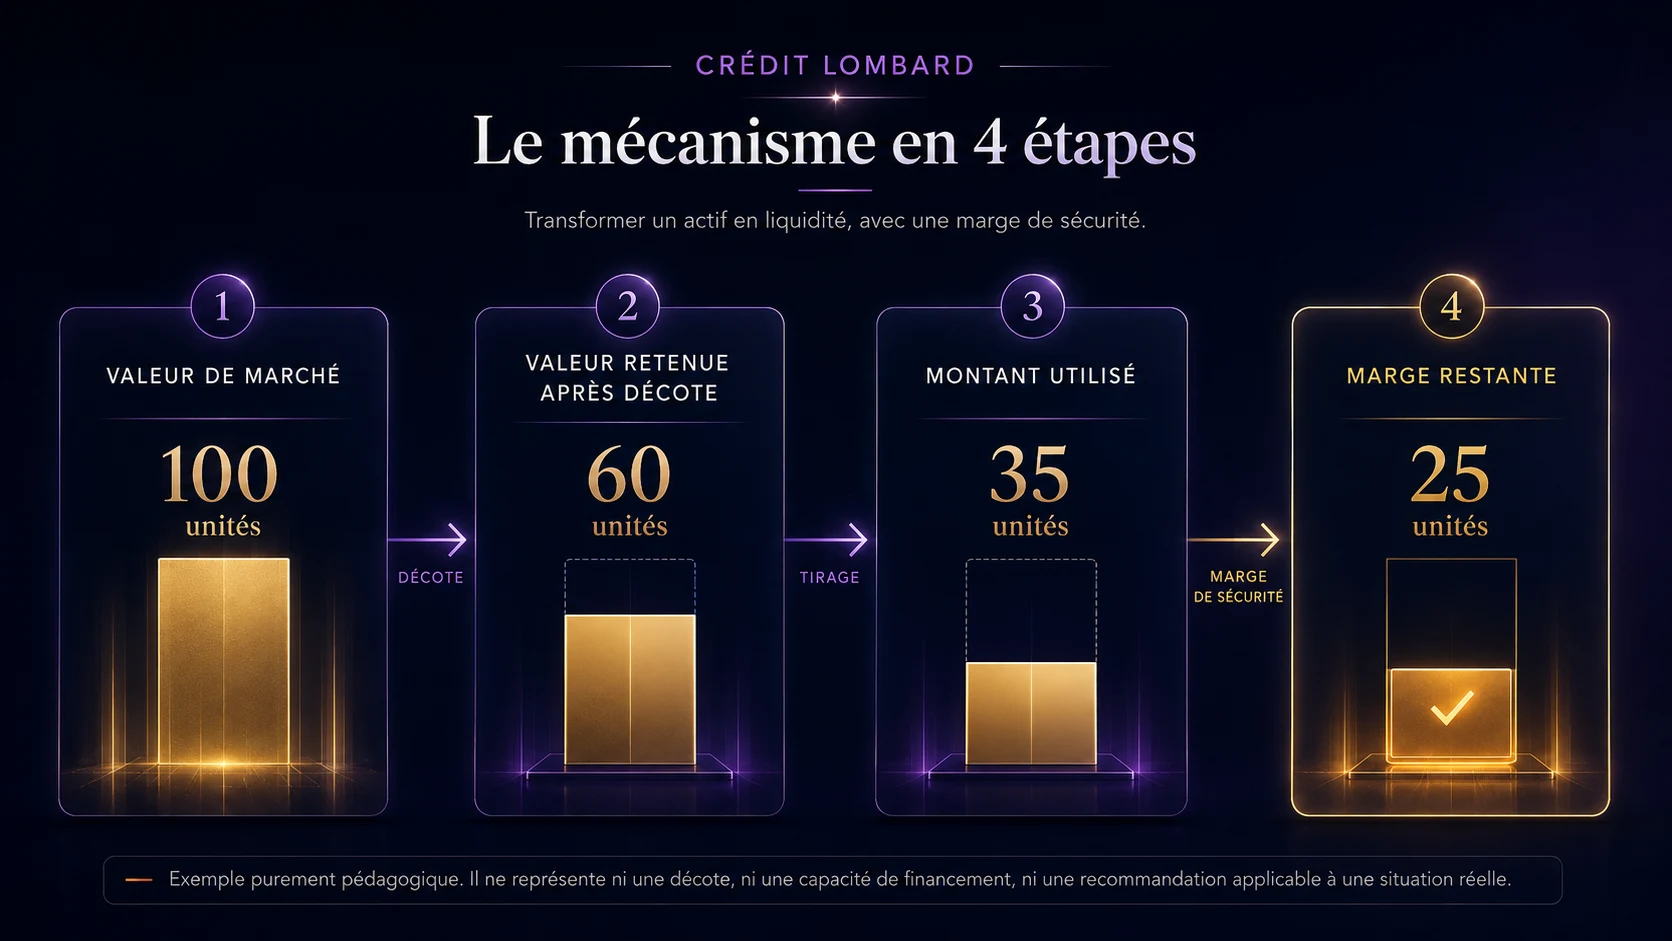
An example to understand the margin
- 01 Market value 100 units
- 02 Collateral value after the haircut 60 units
- 03 Amount borrowed 35 units
- 04 Remaining margin 25 units
For illustration only. These figures are not a lending haircut, borrowing capacity or recommendation for an actual situation.
- Identify assets that the lender agrees to study.
- Check collateral value after the haircut. It is different from market value.
- Decide how much of the credit limit your project actually needs.
- Keep enough margin to cope with less favourable conditions.
How does the bank value your collateral?
This depends on the lender, the agreement and the assets. An asset may have a market value yet count for little or nothing as collateral. There is no universal threshold, rate or loan-to-value ratio on this page.
Margin reduction
Unfavorable scenario
When collateral value falls, your headroom shrinks
The central risk is not only the decline in assets, it is the combination of fluctuating assets, a debt that remains due and clauses that can speed up decisions.
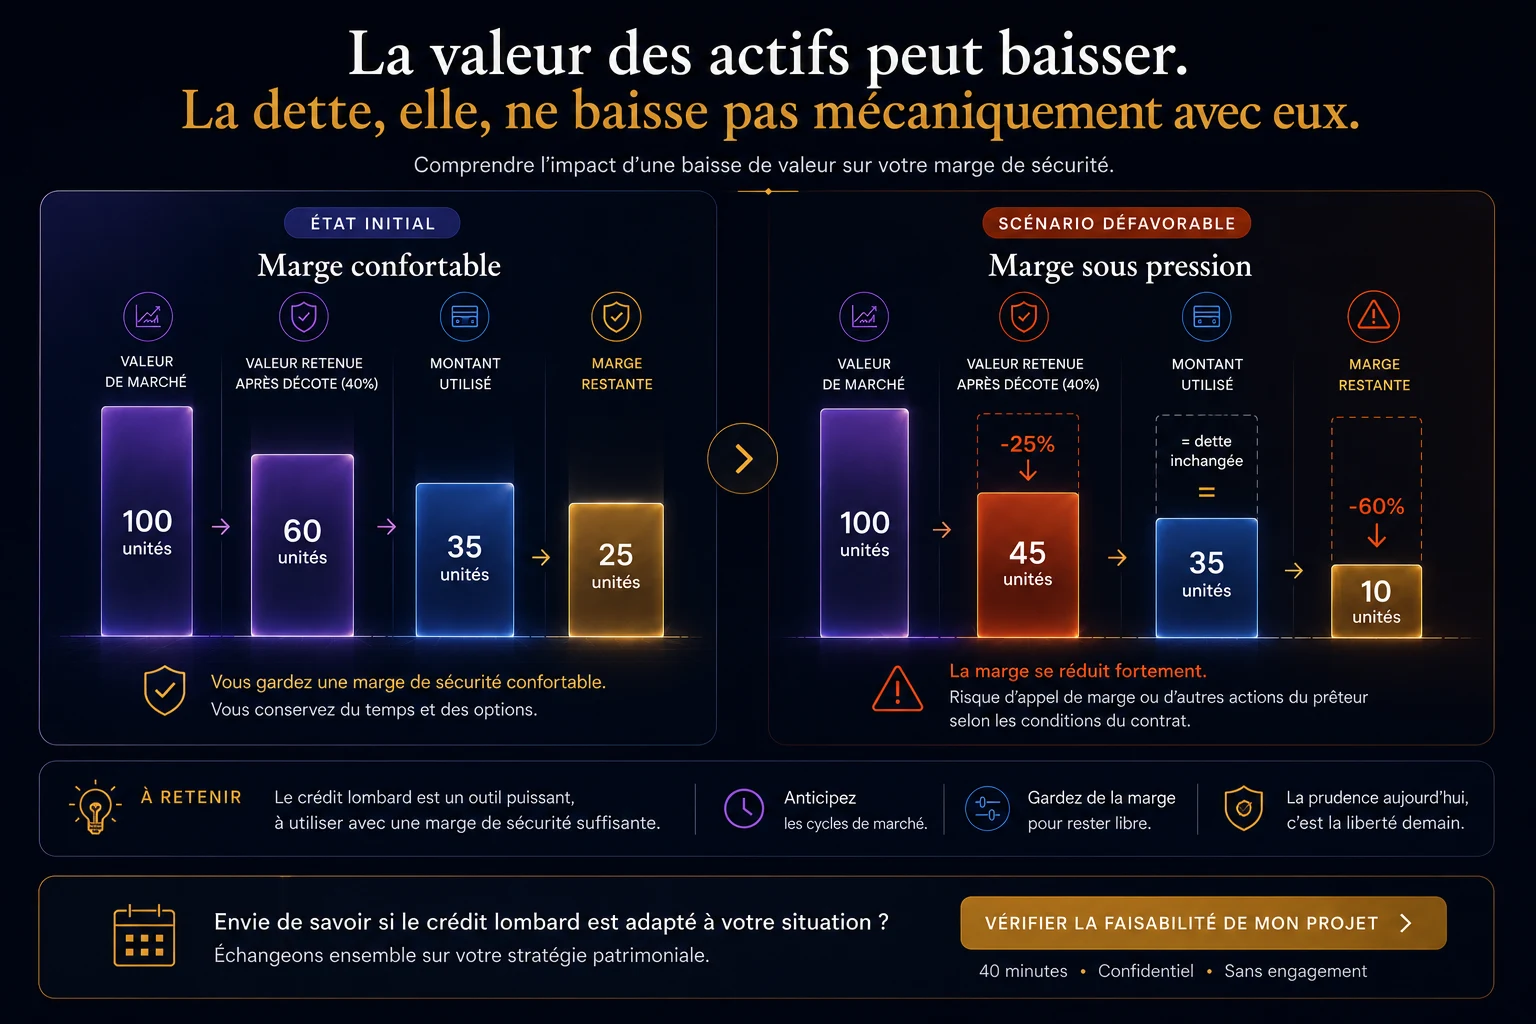
- Collateral value
- 60 units
- Amount borrowed
- 35 units
- Collateral value
- 45 units
- Amount borrowed
- 35 units
Let's discuss the amount you need, your investments and the risks to examine.
40 minutes · Confidential · No obligation
Possible consequences under the contract
- reduction of the limit available
- a request for partial repayment
- request for additional guarantee
- margin call
- sale of securities or assets according to contract
- restrictions on certain movements
A margin call does not guarantee you a protected period in which to act. Deadlines and the lender's powers depend on the agreement.
Terms, interest rates and currency
Which clauses could require you to act quickly?
The banking documents cited are identified examples, never universal rules.
| Term | Question to ask |
|---|---|
| Eligible assets | What assets are accepted, excluded or valued at zero? |
| Guarantee value | How is collateral value calculated, and can it change? |
| Credit limit | Can the limit be reduced and under what conditions? |
| Margin call | How will you be notified, how long will you have to respond, and what happens if you do not? |
| Lender action | Does the contract provide for a sale or quick action in certain cases? |
| Use of funds | Is the proposed project authorized or restricted by the institution? |
| Interest rates and fees | What are the base rate, lender's margin, fees and default interest rate? |
| Currency | Does the currency of the loan, assets and project create a foreign exchange risk? |
| Duration and reimbursement | Does the loan have a fixed term, renew automatically, require a final lump-sum repayment or become repayable on demand? |
Interest rates and currency: what to check
- fixed, variable, indexed or base-rate terms
- Lender's margin, additional fees and costs if you default
- currency of loan, assets and project
- how often interest is calculated and debited
- the effect of higher interest rates or an adverse exchange rate
Decision
Is this funding suitable for your project?
The page helps to recognize cases where the study makes sense and those where the margin or clauses make the operation fragile.
Worth examining when
- a project requires liquidity without immediate sale
- the sale would create an unwanted tax, financial or strategic consequence
- the assets are sufficiently transparent, liquid and diversified for the lender to assess
- a realistic source of repayment exists
- other resources are available to cover a stressed scenario
- the financing fits with your wider financial plans
Pause or avoid it when
- the project requires to use all the maximum proposed
- the remaining margin depends on a concentrated or highly volatile portfolio
- the source of repayment remains unclear
- the person could not react quickly to a guarantee request
- The use of funds is prohibited or ambiguous
- you do not understand the tax consequences, currency exposure or terms
Talk it through with Gary
Have a project or a loan offer to review?
40 minutes · Confidential · No obligation · Directly with Gary Martins
9 verifications
What to check before borrowing
Use these questions when reviewing a loan offer, contract or project, before choosing an amount.
- 01
What project do you finance, on what horizon and with what source of reimbursement?
- 02
What assets does the lender actually accept?
- 03
What collateral value is used after the haircut, and how could it change?
- 04
How much of the credit limit will you use?
- 05
What margin remains if the scenario becomes less favourable?
- 06
What time frame, channel and consequences in case of margin call?
- 07
In what cases can the lender sell or close assets?
- 08
What is the total cost, taking account of interest, currency, fees and term?
- 09
What rules apply depending on the residence, assets, contract and country of the lender?
Printable Guide
Lombard loans: nine checks before you commit
A short checklist to help you read a bank's offer and prepare your questions before we speak.
- Print version
- questions to ask the lender
- Schedule of clauses
- interest rate, currency and fee checklist
- preparing your meeting
The full guide
Lombard loans: borrow against your investments without selling them, and know how far to go
A Lombard loan is a bank loan secured by a pledge over your investments, either a securities portfolio or a life insurance policy: you raise cash without selling anything. The bank does not lend against the market value of your assets, but against a lower value, reduced by a haircut specific to each asset. The price you pay: interest, and the risk of a margin call if your investments fall.
I am not a banker or a credit intermediary, and I neither grant nor negotiate any loan. My role is wealth planning: looking at what your policy or your investments can withstand if markets fall, and what the transaction changes for your wealth as a whole. For the financing itself, I simply make an introduction, through Uptimi, to an authorised lender or intermediary: they review the application, advise you on the loan, make the decision and set the terms.
Guide contents (14)
- What is a Lombard loan? A simple definition
- How does a Lombard loan work?
- What is the minimum amount for a Lombard loan?
- What are Lombard loan interest rates?
- Interest-only or amortising: which repayment should you choose?
- Lombard loan example: what can you borrow against an €800,000 policy?
- What is a margin call? The real risk of a Lombard loan
- Can you use a Lombard loan to buy property? In France and abroad
- Lombard loan vs mortgage: what are the differences?
- Borrowing instead of withdrawing: what changes for tax?
- Can you get a Lombard loan against Luxembourg life insurance?
- Which banks offer Lombard loans, and who can get one?
- What about Spain?
- What I review with you before any introduction
What is a Lombard loan? A simple definition
A Lombard loan means borrowing by pledging your investments as collateral, instead of selling them. Lombard lending, Lombard credit and securities-based lending describe the same mechanism, known in France as crédit lombard and in Spain as préstamo lombardo.
It brings together five elements:
- the pledged assets: securities accounts, life insurance or capitalisation policies, sometimes cash;
- the lending value: the market value of each asset multiplied by a loan-to-value ratio set by the bank;
- the form of the loan: a fixed-term advance or a credit line you draw on as needed;
- the interest rate: variable or fixed, depending on the bank;
- monitoring of the cover: the bank regularly recalculates the value of your collateral.
How does a Lombard loan work?
The bank adds up the lending value of each pledged asset; you can borrow up to that total, and the bank then checks that the collateral remains sufficient. The steps:
- You identify the assets to pledge.
- The bank assigns each one a loan-to-value ratio based on its liquidity, volatility, currency and concentration.
- You sign the pledge agreement. For a life insurance policy governed by French law, this is done by endorsement or by deed, and if a beneficiary has already accepted the policy, their consent is required (article L. 132-10 of the French Insurance Code (code des assurances)).
- The funds are paid out in one go or made available to draw.
- The cover is monitored for the whole life of the loan.
| Asset class | Loan-to-value commonly observed (indicative) |
|---|---|
| Cash, money market funds | 80% to 95% |
| Bonds from highly rated issuers | 60% to 85% |
| Diversified or bond funds | 50% to 75% |
| Large-cap equities, broad ETFs | 40% to 70% |
| Structured products | 0% to 70% depending on the issuer and the capital protection |
| Small caps, alternative funds, unlisted assets | 0% to 30% |
These ranges are market orders of magnitude, not a rate card: each bank publishes or provides its own grid, and may give an asset a loan-to-value of zero.
Run your own simulation in three lines:
- Borrowing capacity = sum of (value of each asset × its loan-to-value).
- Safety margin = capacity − amount borrowed.
- Utilisation rate = amount borrowed ÷ capacity. Above 60%, I consider you exposed.
What is the minimum amount for a Lombard loan?
There is no legal minimum; each bank sets its own, and private banks typically start at around €100,000 of credit. The pledgeable financial assets required usually run to several hundred thousand euros, because the bank only lends a fraction of their value.
The minimum is not the only filter. The bank also looks at your profile (income, source of funds, tax residence), the quality of the assets, what the money will be used for and, often, the overall relationship you will have with it.
What are Lombard loan interest rates?
A Lombard loan rate is usually variable: a benchmark index, generally Euribor, plus a margin specific to each bank. Some banks also offer a fixed rate on short-term advances.
For reference: 3-month Euribor was around 2.6% in September 2026 (monthly average published on the ECB data portal). This figure moves every day and is not the rate on your loan.
The bank's margin depends on the amount, the quality of the pledged assets, the term and the overall relationship. I do not publish a margin range: it varies too much from one bank and one case to another to be useful. Also factor in arrangement fees, a possible commitment fee on the undrawn part of a credit line, and currency risk if you borrow in a currency other than that of your assets or your income.
Interest-only or amortising: which repayment should you choose?
Most Lombard loans are interest-only (bullet repayment): you pay interest during the loan and repay the capital at maturity, often with the option to roll it over. Some banks still offer amortising repayment.
On €400,000 at a hypothetical rate of 4% a year (calculation assumption, not an offer):
- interest-only: €16,000 of interest a year, or about €1,333 a month, with the capital due at the end;
- amortising over 15 years: about €2,959 a month, for total interest of about €132,600.
Interest-only protects your cash flow but requires a clear repayment plan: selling the property, a partial withdrawal from the policy, the sale of another asset.
First meeting free of charge
40 minutes by video call, confidential, directly with me.
Book my free first meetingLombard loan example: what can you borrow against an €800,000 policy?
Illustrative example. Assumptions: an €800,000 life insurance policy pledged, loan-to-value ratios set for the purpose of the example, €400,000 borrowed interest-only to buy a property. None of these figures corresponds to an actual offer.
| Part of the policy | Value | Loan-to-value applied (assumption) | Lending value |
|---|---|---|---|
| Money market | €80,000 | 90% | €72,000 |
| Bonds and structured products | €320,000 | 65% | €208,000 |
| Equities and ETFs | €400,000 | 55% | €220,000 |
| Total | €800,000 | €500,000 |
The bank could lend up to €500,000. You borrow €400,000: you are using 80% of the capacity, with a €100,000 margin.
| Scenario | Policy value | Lending value | Margin with €400,000 borrowed | Margin with €300,000 borrowed |
|---|---|---|---|---|
| Start | €800,000 | €500,000 | + €100,000 | + €200,000 |
| Moderate fall (equities − 15%, bonds and structured products − 5%) | €724,000 | €456,600 | + €56,600 | + €156,600 |
| Sharp fall (equities − 35%, bonds and structured products − 15%) | €612,000 | €391,800 | − €8,200: margin call | + €91,800 |
In the sharp-fall scenario, the policy has lost 23.5% of its value, yet the margin on €400,000 borrowed has gone. With €300,000 borrowed, the same shock passes without a margin call.
And what if you withdrew €400,000 instead? For a French tax resident: if gains make up 25% of the policy value (€200,000 of gains on €600,000 of premiums paid), a €400,000 withdrawal brings out €100,000 of taxable gains: €17,200 of social charges, plus income tax. If the policy is under 8 years old: 12.8%, so €30,000 in total. After 8 years: an allowance of €4,600 (€9,200 for a couple), then 7.5% on the share of gains relating to €150,000 of premiums per person and 12.8% above that, so about €26,400 (couple) to €28,100 (single person). In total, roughly between €26,000 and €30,000. The loan avoids this tax today, but at €16,000 of interest a year it becomes more expensive than a withdrawal after about two years. A Lombard loan is therefore justified by a time horizon and an expected return, never by tax alone.
What is a margin call? The real risk of a Lombard loan
When the lending value of your collateral falls below the amount borrowed, or below a warning threshold set in the contract, the bank makes a margin call. You then have to repay part of the loan, provide other assets, or accept that the bank enforces the collateral, meaning it sells the pledged assets or has them surrendered. On a life insurance policy governed by French law, the pledgee can trigger a surrender of the policy, unless the contract says otherwise (article L. 132-10 of the French Insurance Code).
What makes this risk serious:
- the response deadlines are set by the contract and can be very short;
- the sale often happens at the worst moment, turning a temporary fall into a permanent loss;
- a single concentrated position, or an asset that becomes ineligible, can make the lending value drop sharply.
My own safety rules: use only part of the capacity, diversify the collateral, keep cash outside the pledge, avoid a currency mismatch.
Can you use a Lombard loan to buy property? In France and abroad
Yes, a Lombard loan can finance property: a main or second home, a buy-to-let, or a cash purchase before selling another property, in France or abroad. It is often what lets you buy quickly, without a long financing condition in the purchase contract, or finance a property abroad that a French bank would not fund with a mortgage. The bank may nonetheless ask for a mortgage as additional security.
Does a Lombard loan escape France's 35% HCSF rule?
No, not automatically: that is a common misconception. The decision of the HCSF (France's High Council for Financial Stability) applies to the loans covered by article L. 313-1 of the French Consumer Code (code de la consommation), that is, in particular, loans intended to finance the purchase of a home, granted to borrowers located in France or intended to finance assets located in France (article 3 of decision D-HCSF-2021-7). The only exclusions provided for are bridging loans, renegotiations, refinancing with another lender and debt consolidation. The type of security, a pledge rather than a mortgage, plays no part in this test.
What this means:
- a Lombard loan used by a borrower located in France to buy a home falls, in principle, within scope: a debt-to-income ratio of 35% maximum and a term of 25 years maximum;
- the bank may depart from these criteria for up to 20% of its quarterly lending, of which at least 70% is reserved for buying a main residence (decision D-HCSF-2023-2 of 29 June 2023): the free portion, usable for a buy-to-let or a second home, is therefore limited to 6% of lending;
- a Spanish resident buying in Spain, or a loan with no residential property purpose, falls outside this framework.
The debt-to-income ratio is calculated on the maximum annual payments of all your loans over their term (article 4 of the decision). How an interest-only repayment backed by financial assets is treated in this calculation is a point to have the lending bank confirm in writing before you launch the project.
Lombard loan vs mortgage: what are the differences?
A traditional French mortgage relies on your income and on the property; a Lombard loan relies first and foremost on your financial assets.
| Lombard loan | Traditional French mortgage | |
|---|---|---|
| Security | Pledge over investments | Mortgage or loan guarantee (caution) |
| Term | Short, often renewable | 15 to 25 years |
| Repayment | Usually interest-only | Amortising |
| Rate | Usually variable, fixed possible on short-term advances | Usually fixed |
| Borrower insurance | Rarely required, depending on the bank | Generally required |
| Set-up | Fast once the application is complete | Longer |
| HCSF criteria | Apply if the purpose is a home and the loan falls within scope | Apply |
| Main risk | Margin call if markets fall | Payment default |
Borrowing instead of withdrawing: what changes for tax?
For a French tax resident, as long as you do not withdraw, your gains are not taxed: a life insurance policy is taxed when you make a withdrawal. A Lombard loan therefore defers the tax; it does not eliminate it.
The interest:
- unfurnished buy-to-let: interest is deductible from rental income (revenus fonciers) if the borrowed funds were actually used to acquire or improve the let property, which you must be able to prove; the tax authorities also accept the deduction for an interest-only loan (BOFiP, BOI-RFPI-BASE-20-80, § 20, 270 and 290);
- furnished letting taxed on actual expenses (régime réel): interest is deductible if it meets the general conditions for deducting expenses from business income (BIC), meaning the loan was taken out in the interest of the letting activity and the expense is justified (impots.gouv.fr, "Location meublée : les régimes d'imposition");
- main or second home, investments: no deduction.
Can you get a Lombard loan against Luxembourg life insurance?
Yes, it is one of the most common structures: the Luxembourg policy is pledged to the bank, often its depositary bank, and your assets keep working. Three points to check before opening the policy, not after:
- does the bank accept each investment as collateral, and at what loan-to-value? A dedicated fund loaded with illiquid assets may be worth almost nothing as collateral;
- does the loan currency match that of the policy and of the project?
- is the structure compatible with your current and future country of residence?
Everything else about the policy is covered on my Luxembourg life insurance page.
Which banks offer Lombard loans, and who can get one?
Lombard loans are mainly offered by private banks: those of the major French banking groups, Luxembourg and Swiss banks, and the depositary banks of Luxembourg policies. The right lender depends first of all on where your assets are held.
They are open to individuals, resident or non-resident, and to family holding companies, provided you hold assets the bank accepts and pass its checks (identity, source of funds, tax residence). Business owners after selling their company and people with invested private wealth are the most frequent profiles.
My role: looking at the transaction within your wealth as a whole (pledged policy, horizon, downside scenario), then introducing you, through Uptimi, to an authorised lender or intermediary suited to your situation. I take no part in negotiating the loan or in advising on the loan itself. If the collateral is a securities account, I do not advise on the securities either. It is always the bank that accepts or declines.
What about Spain?
In Spain, the same mechanism exists under the name "préstamo lombardo": a loan secured by a pledge over securities or over a policy, offered mainly by private banks. For a Spanish resident buying in Spain, the HCSF criteria do not apply, but the Spanish tax treatment of the pledged policy and the reporting obligations must be checked before signing. See my page on expats in Spain.
What I review with you before any introduction
My analysis covers your wealth and the policy given as collateral, not the loan itself, which is the bank's business.
- The repayment plan: where will the capital come from at maturity?
- The safety margin: how much margin would be left after a sharp market fall, rather than the maximum the bank might offer.
- The pledged policy or assets: diversification, liquidity, currency; for a securities account, I limit myself to observations, without advice on the securities.
- The crisis scenario: what happens if equities lose a third?
- The cost of a withdrawal: what a withdrawal from your policy would cost, to compare with the total cost the bank will quote you.
- The questions to ask the bank: purpose of the loan and application of the HCSF criteria, country of the property and country of residence, margin call threshold, time allowed to respond, cases in which the collateral is enforced, renewal conditions. Its written answers are what count.
The mistakes I see most often: borrowing the maximum the bank offers, pledging a single concentrated position, financing an illiquid asset with no exit plan, and believing a Lombard loan is a tax trick.
Key takeaways
- A Lombard loan lends against the value of your investments after a haircut, without selling them.
- The rate is usually variable: Euribor + margin (3-month Euribor: around 2.6% in September 2026).
- The central risk is the margin call: use only part of your capacity.
- It is not automatically outside the HCSF criteria when it finances a home.
- It defers tax on gains; it does not eliminate it.
First meeting free of charge
Want to know whether your project stands up? The first 40-minute call is free, confidential, by video. Together we look at your assets, a reasonable amount to borrow and the downside scenario, before any approach to a bank. I work in English, French, Spanish and Portuguese.
Book my free first meetingOfficial sources
- Légifrance – Decision no. D-HCSF-2021-7 of 29 September 2021 on the conditions for granting home loans (in French)
- Légifrance – Article 3 of decision D-HCSF-2021-7 (scope) (in French)
- Légifrance – HCSF decision of 29 June 2023 (allocation of the flexibility margin) (in French)
- Légifrance – HCSF decision of 18 December 2023 (bridging loans, renovation works) (in French)
- ORIAS – Ordinance no. 2016-351 of 25 March 2016 (text of article L. 313-1 of the French Consumer Code) (in French)
- Légifrance – Article L. 132-10 of the French Insurance Code (pledge of a life insurance policy) (in French)
- ECB Data Portal – 3-month Euribor, monthly average (series FM.M.U2.EUR.RT.MM.EURIBOR3MD_.HSTA)
- BOFiP – BOI-RFPI-BASE-20-80: rental income, loan interest and borrowing costs (in French)
- Service-Public.gouv.fr – Life insurance: taxation of gains on withdrawal (fact sheet F22414, checked on 15 April 2026) (in French)
- French National Assembly – Information report no. 2983 on the impact of the debt-to-income ratio set by the HCSF (24 June 2026) (in French)
- economie.gouv.fr – HCSF measure on the granting of home loans (20% flexibility, of which 70% for main residences) (in French)
- impots.gouv.fr – Furnished lettings: tax regimes (conditions for deducting actual expenses, updated on 8 April 2026) (in French)
Texts checked on 29 October 2026. This content is for information only and does not replace a review of your situation.
Questions and sources
The questions to answer before choosing a loan amount
Can a Lombard loan really let me avoid selling my investments?
It can avoid an immediate sale. But the assets are given as collateral and can be sold in certain scenarios under the contract.
Is the amount proposed by the bank necessarily prudent?
Not necessarily. The bank's limit reflects its lending and collateral rules. Your own financial position may call for borrowing less than the maximum offered.
Are all financial assets eligible?
No. Eligibility depends on the institution, contract, liquidity, volatility, currency, concentration and type of asset.
Can a Luxembourg life insurance policy always be pledged as collateral?
No. This needs checking for the specific policy, insurer, custodian, lender, investments, beneficiary, country of residence and applicable rules. Understanding the functioning of Luxembourg life insurance
Does a margin call always give me time to react?
No. Contractual conditions prevail. Time limits can be very short and some contracts provide for quick action in specific circumstances.
What is a Lombard loan?
It is a bank loan secured by a pledge over your investments (a securities portfolio or a life insurance policy). You raise cash without selling; the bank lends against a value reduced by a haircut specific to each asset, and can ask for more collateral if that value falls.
What is the minimum amount for a Lombard loan?
There is no legal minimum: each bank sets its own. In practice, private banks often start at around €100,000 of credit, with pledgeable financial assets of several hundred thousand euros.
What is the interest rate on a Lombard loan?
Usually a variable rate equal to an index (Euribor) plus a margin specific to each bank; some banks offer a fixed rate on short-term advances. For reference, 3-month Euribor was around 2.6% in September 2026.
Can you use a Lombard loan to buy property?
Yes, in France and abroad: a main or second home, a buy-to-let, or a cash purchase before selling another property. The bank may still ask for additional security, and the loan always remains subject to its approval.
Does France's 35% HCSF debt-to-income rule apply to Lombard loans?
Lombard loans are not automatically excluded. The HCSF decision covers loans intended in particular to buy a home, granted to borrowers located in France or for a property located in France, whatever the security; a Lombard loan that finances a home is therefore in principle within scope, and the bank can grant it within its exemption allowance.
Can you get a Lombard loan against a Luxembourg life insurance policy?
Yes, it is a common structure: the policy is pledged to the bank, with no withdrawal. The bank accepts or rejects each investment, applies its own haircut and can trigger a surrender of the policy if you default.
What happens to a Lombard loan if markets fall?
If the collateral value falls below the amount lent, the bank makes a margin call: you repay part of the loan, provide other assets, or the bank enforces the collateral. The deadlines are set by the contract and can be very short.
Which banks offer Lombard loans?
Mainly private banks: those of the major French banking groups, Luxembourg and Swiss banks, and the depositary banks of Luxembourg life insurance policies. The right lender depends on where your assets are held and on your country of residence.
Sources used for this page
These sources include institutional publications, legal texts and examples from lenders. They help explain the subject but do not replace your contract or an individual review.
Institutional sources
- CSSF — Questions and answers on Circular 22/824
Luxembourg's prudential framework and transparency requirements within its scope.
- CSSF — Circular 22/824 and EBA guidelines
Loan governance, origination, valuation and monitoring; not a substitute for an individual contract.
- ACPR — French Banking and Insurance Authority
General institutional source, not specific product documentation.
- CAA Luxembourg — Insurance supervision
General institutional source. It does not establish the eligibility of a particular policy.
Legal texts
- Légifrance — French Insurance Code, Article L132-10
French legal reference on pledging an insurance policy; it does not confirm a bank's acceptance.
- Légifrance — French Monetary and Financial Code, Article L211-20
French legal reference on pledging a securities account and the formal requirements.
Bank or contractual documentation used as examples
- Swissquote — Lombard lending: flexible financing
Example of bank offer, without generalisation of permitted rates, currencies or uses.
- Swissquote — Secured loan agreement
Contractual example identified to read the lender's margin, limit and action clauses.
- UBS — Lombard loans FAQ
Lender FAQ explaining risk, safety margins, interest rates and currencies.
- Lombard Odier — Base rates for fixed-term loans
Example of reading base rates by currency, without Martins Patrimoine rates.
- BoursoBank — What is a Lombard loan?
Example of an institution-specific offer and restrictions.
- BoursoBank — Luxembourg life insurance and Lombard loan
Example showing that a Luxembourg contract is not automatically accepted everywhere.
Conclusion
Let's discuss your project and the margin you need to keep
Collateral value, amount borrowed, a fall in value, interest rates, currency and terms: the first conversation helps decide whether a detailed review is worthwhile.
40 minutes · Confidential · No obligation · Directly with Gary Martins